The headline economic story in Australia at the moment is well-known to anyone reading the business pages. Growth is modest, consumer confidence is subdued, the construction pipeline is not what it was two years ago, and the interest-rate environment is doing what interest-rate environments do to capital-intensive activity. From the outside, that reads as bad news for steel.
From inside the industry it reads as something more nuanced. Steel demand is cyclical by nature, and the sector is used to reading cycles. What matters is not whether we are in a soft patch but what kind of soft patch it is, which segments are absorbing the pressure, and which underlying drivers remain in place through the cycle. Thirty years in Australian and Southeast Asian steel has taught me to distrust both the doom-loop headlines and the reflexive optimism from within the industry. The truth usually sits in the segment-level detail.
THE SOFT SEGMENTS
Residential construction is the most visible weak point. Approvals have slowed, developer pipelines have thinned, and the flow-through to structural steel, reinforcing bar, roofing coil and cladding is meaningful. A meaningful share of Australia’s coated-steel and long-product demand runs through housing, so any prolonged softness there shows up quickly in mill and distributor order books.
Commercial construction is doing better than residential in some cities and worse in others, and the story is very location-specific. Sydney and Melbourne CBD office markets have their own dynamics that do not necessarily correlate with Perth or Brisbane. Anyone drawing a single national trend line on commercial steel demand is oversimplifying.
Discretionary manufacturing that consumes steel as an input – appliances, furniture, small-run fabrication – is soft where consumer demand is soft. This is the segment where the drag is most direct.
THE RESILIENT SEGMENTS
Infrastructure is the counterweight. The scale of civil infrastructure spending currently committed across state and federal programmes is significant, and it consumes steel in volumes that partially offset residential softness. Rail, roads, water infrastructure, energy-transmission projects and defence build-outs are all steel-intensive and largely insulated from short-term consumer-sentiment cycles.
Renewable-energy build-out is a category that did not really exist as a demand driver a decade ago and is now consequential. Wind-farm towers, solar-farm mounting systems, transmission infrastructure and battery-storage sites all consume structural steel, and the pipeline is long-dated. This is a durable demand source that runs through most cyclical downturns.
Mining and resources continues to consume steel for maintenance and capital work regardless of the domestic consumer cycle. When commodity prices are firm, capital work accelerates. When they are soft, maintenance work continues. Either way, the sector is a steady demand base rather than a swing factor.
THE IMPORT DIMENSION
The other thing worth noting in a slow domestic cycle is what happens to imports. When domestic construction cools, the pull on imported product should ease, but the market does not always work that way. Trading houses with pre-existing supply commitments still land product. Mills in other markets under their own oversupply pressure look for buyers where they can find them. So a slow domestic cycle can co-exist with continued or even elevated imported-steel volumes, which puts additional pressure on domestic-produced margins.
This is one of the reasons the anti-dumping conversation stays live in Australia even when consumption is soft. It is not really about whether domestic demand is up or down. It is about whether the imported product landing here is doing so at prices that reflect the true cost of manufacture in the origin market. That is a separate question, and worth its own treatment.
WHAT IT LOOKS LIKE ON THE OPERATOR SIDE
For operators inside the industry, three practical things follow from a soft domestic cycle.
The first is that segment discipline matters. Distributors and fabricators who serve a broad customer base across residential, commercial, infrastructure and industrial can smooth their order book. Operators concentrated in a single soft segment do not have that luxury. This is not a new lesson, but it is a lesson the industry re-learns every cycle.
The second is that working-capital discipline becomes disproportionately important. In a soft market, buyers stretch. Payment terms slip. Inventory builds. The businesses that come through cycles well are the ones who watched receivables, cycled inventory hard and did not carry balance sheet through the trough. Ones who did not, do not.
The third is that customer relationships built in the good years earn their keep in the bad ones. The buyer who was properly supported through the last cycle is more likely to remain loyal through this one. The buyer who was transactionally optimised in favour of the seller is more likely to shop the market. Steel is a relationship business over long horizons, and the current cycle is a reminder of why.
THE LONGER PICTURE
None of this means the Australian steel industry is in trouble. Underlying long-run demand drivers – population growth, infrastructure need, decarbonisation build-out, resources capital expenditure – remain in place. What has changed is the near-term momentum, and that is a cyclical variable rather than a structural one.
The operators best positioned for the next up-cycle are the ones running the current soft patch with discipline: holding customer relationships, managing working capital, refusing to over-discount into unsustainable pricing, and using the lower-activity period to invest in the operational improvements that pay back when volume returns. That is how the good businesses in this sector have always come through cycles, and there is no reason to think this cycle will be different.
CLOSING
Australia’s economy is doing what economies do when interest rates are high and consumer confidence is soft. Steel demand is reflecting that in the segments most exposed to it, and holding up in the segments least exposed. It is not a crisis. It is a cycle. The businesses that treat it as a cycle – and stay disciplined through it – will be in better shape when the cycle turns, which it always does.
That is the observation from thirty years of watching Australian steel through its cycles. The current one is uncomfortable in places. It is not, in any structural sense, a break from what this sector has weathered before.
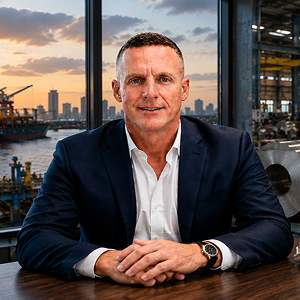
Jason Thomas Ellis
Jason Thomas Ellis is Executive Chairman of iTrade Steel Pty Ltd and Chairman of Empower Steel Australia Pty Ltd. He has held senior leadership roles across BlueScope Steel, Tata BlueScope Steel, Commercial Metals Company, Butler and BHP Lysaght, operating businesses across Australia, India, China, Thailand, Cambodia, Laos, Myanmar and Sri Lanka. He holds a BA (Political Science) from the University of Sydney and an MCom (Finance) from the University of Wollongong, and is a Fellow of the Australian Institute of Company Directors.